Know about Profitability Ratios (with example) and their Significance
Table of contents
Profitability ratios measure a company’s ability to generate profit relative to its revenue, assets, equity, or other financial metrics. These ratios help assess a business’s efficiency in using its resources to produce earnings. Here are some common profitability ratios, along with examples and their significance:
1. Gross Profit Margin
The gross profit margin ratio measures the percentage of revenue that exceeds the cost of goods sold (COGS). It reflects how efficiently a company produces its products relative to its direct costs.
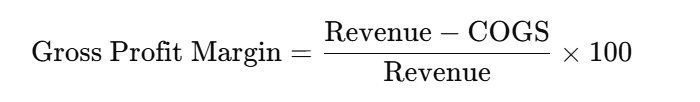
Example:
If a company has revenue of ₹1,00,000 and COGS of ₹60,000, the gross profit margin would be:
(1,00,000−60,000) x100/1,00,000×100=40%
This means 40% of the revenue is retained as gross profit, indicating efficiency in production cost management.
Significance:
A higher gross profit margin shows that a company can cover its production costs and still have a portion of revenue left for other expenses. It’s useful for comparing companies within the same industry.
2. Operating Profit Margin
The operating profit margin shows the percentage of revenue remaining after all operating expenses (excluding interest and taxes) are subtracted from gross profit. It’s calculated as:
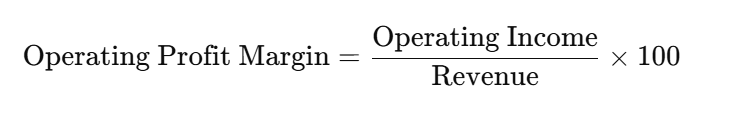
Example:
If a company has operating income of ₹20,000 and revenue of ₹1,00,000, the operating profit margin would be:
20,000×100/1,00,000=20
This indicates that 20% of the revenue remains after accounting for operating expenses, which reflects operational efficiency.
Significance:
Operating profit margin reveals how well a company manages its fixed and variable costs. A higher margin signifies better cost control and profitability from core business activities.
3. Net Profit Margin
The net profit margin measures the percentage of revenue that remains as profit after all expenses, including interest and taxes, are deducted. It’s calculated using:
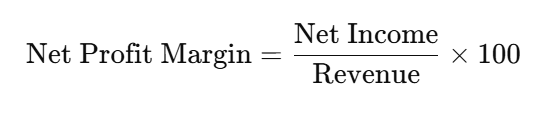
Example:
If a company has net income of ₹15,000 and revenue of ₹1,00,000, the net profit margin would be:
15,000×100/1,00,000=15
This means 15% of the revenue is left as net profit, which shows the company’s overall profitability.
Significance:
The net profit margin is crucial for assessing overall profitability and cost efficiency. A higher net margin implies strong profitability after accounting for all expenses.
4. Return on Assets (ROA)
The return on assets (ROA) ratio indicates how effectively a company uses its assets to generate profit. It’s calculated as:
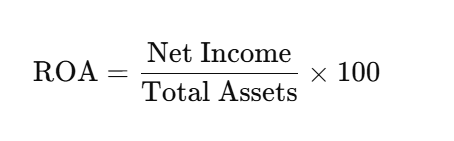
Example:
If a company has net income of ₹10,000 and total assets of ₹1,00,000, the ROA would be:
10,000×100/1,00,000=10%
This means the company generates a 10% profit on its assets.
Significance:
A higher ROA indicates efficient use of assets. It’s particularly helpful for comparing asset-based profitability among companies in asset-intensive industries, like manufacturing.
5. Return on Equity (ROE)
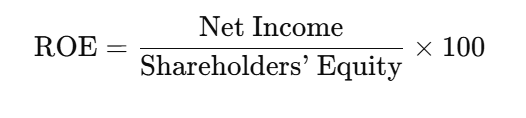
The return on equity (ROE) measures a company’s ability to generate profit from its shareholders’ equity, reflecting the return investors earn on their investment. It’s calculated as:
Example:
If a company has net income of ₹12,000 and shareholders’ equity of ₹80,000, the ROE would be:
12,000×100/80,000=15
This means the company generates a 15% return on shareholders’ investment.
Significance:
ROE is a key metric for investors, as it indicates how well a company uses equity to generate profits. A higher ROE is typically a sign of good management performance.
Importance of Profitability Ratios
Profitability ratios are essential for understanding a company’s efficiency in generating profit, cost management, and overall financial performance. Investors, analysts, and management use these ratios to assess competitive positioning, make informed investment decisions, and improve operational strategies. Comparing profitability ratios with industry standards also provides insights into how well a company performs relative to its peers.
Know more: Know About Liquidity Ratios, their Significance and Examples
Rajesh Pant is a Civil Engineer and Infrastructure Management professional with approximately 25 years of experience in the planning, implementation, coordination, management and execution of large-scale government infrastructure projects. His professional experience encompasses project management, procurement, contract administration, construction management and quality control of infrastructure projects.
He also possesses nearly eight years of experience in Externally Aided Projects (EAPs), particularly in project implementation, procurement and contract management of World Bank-funded projects. His professional exposure includes working with projects financed by multilateral development organisations, providing valuable insights into international procurement practices, project implementation frameworks and contract management requirements.
He holds a Master of Technology (M.Tech.) in Civil Engineering and a Master of Business Administration (MBA) in Infrastructure Management, combining technical engineering expertise with management and administrative capabilities.
With extensive experience in public infrastructure development and government project management, Rajesh brings a practical, multidisciplinary perspective to the fields of contract management, procurement, project management and construction management.